
On 22 October 2024, four days after the biggest homebuilder ETF set its all-time high, PulteGroup's chief executive Ryan Marshall said the Fed's turn to lower rates "provides a powerful tool in helping to address the affordability challenge faced by today's homebuyers." His company, he added, was "well positioned to deliver a record year of earnings."
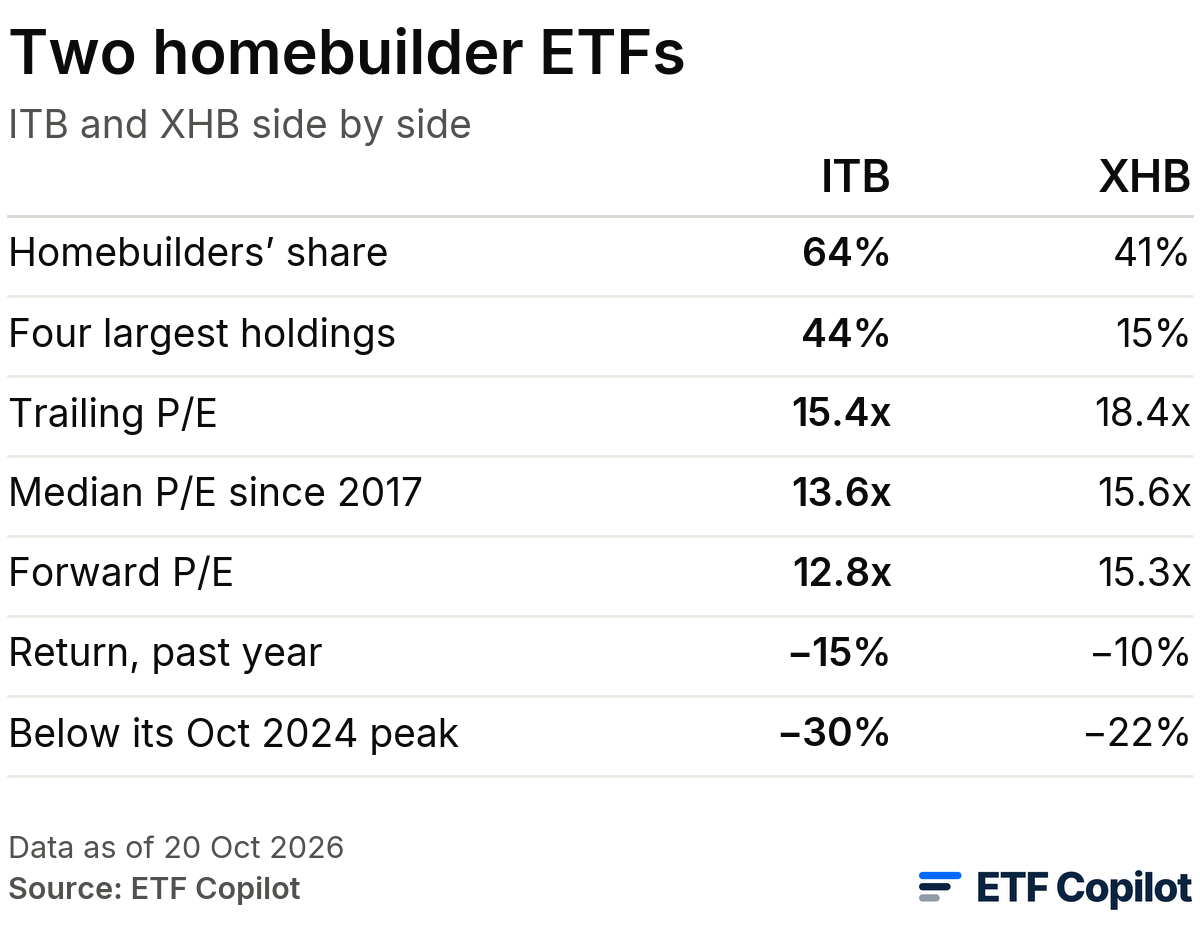
Two years later, ITB, the iShares U.S. Home Construction ETF, is 30% below that high.
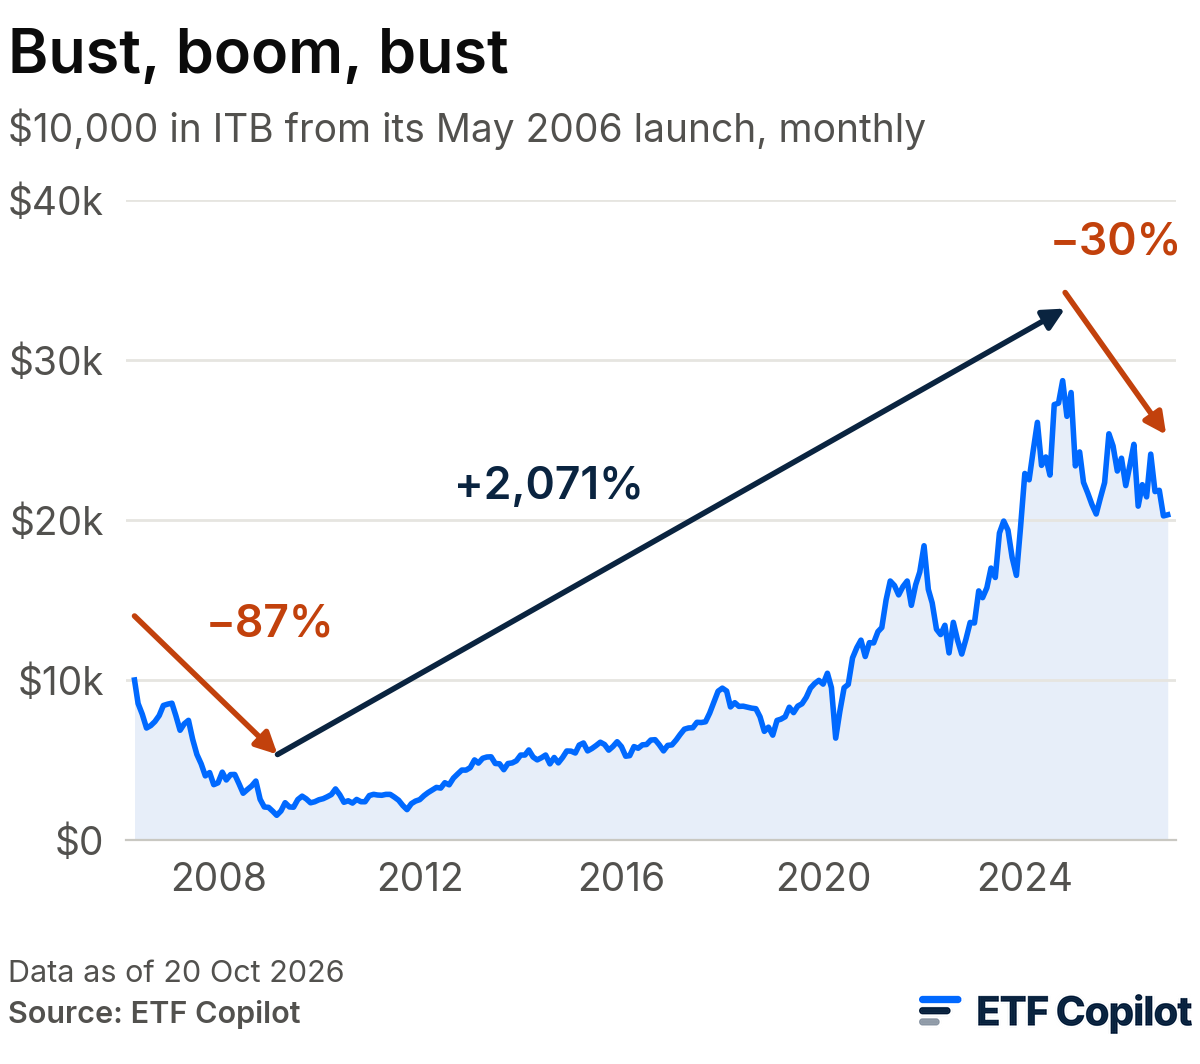
Bust, boom, bust
ITB opened for trading in May 2006, close to the top of the last housing boom. By March 2009 it had lost seven-eighths of its value, and it climbed back to its launch price only in January 2018.
Then came a long climb: from the 2009 low to October 2024, ITB rose about 22-fold, dividends included. The starting point still decided much of the result. Twenty years after launch, ITB has roughly doubled, while the S&P 500 has grown more than eightfold.
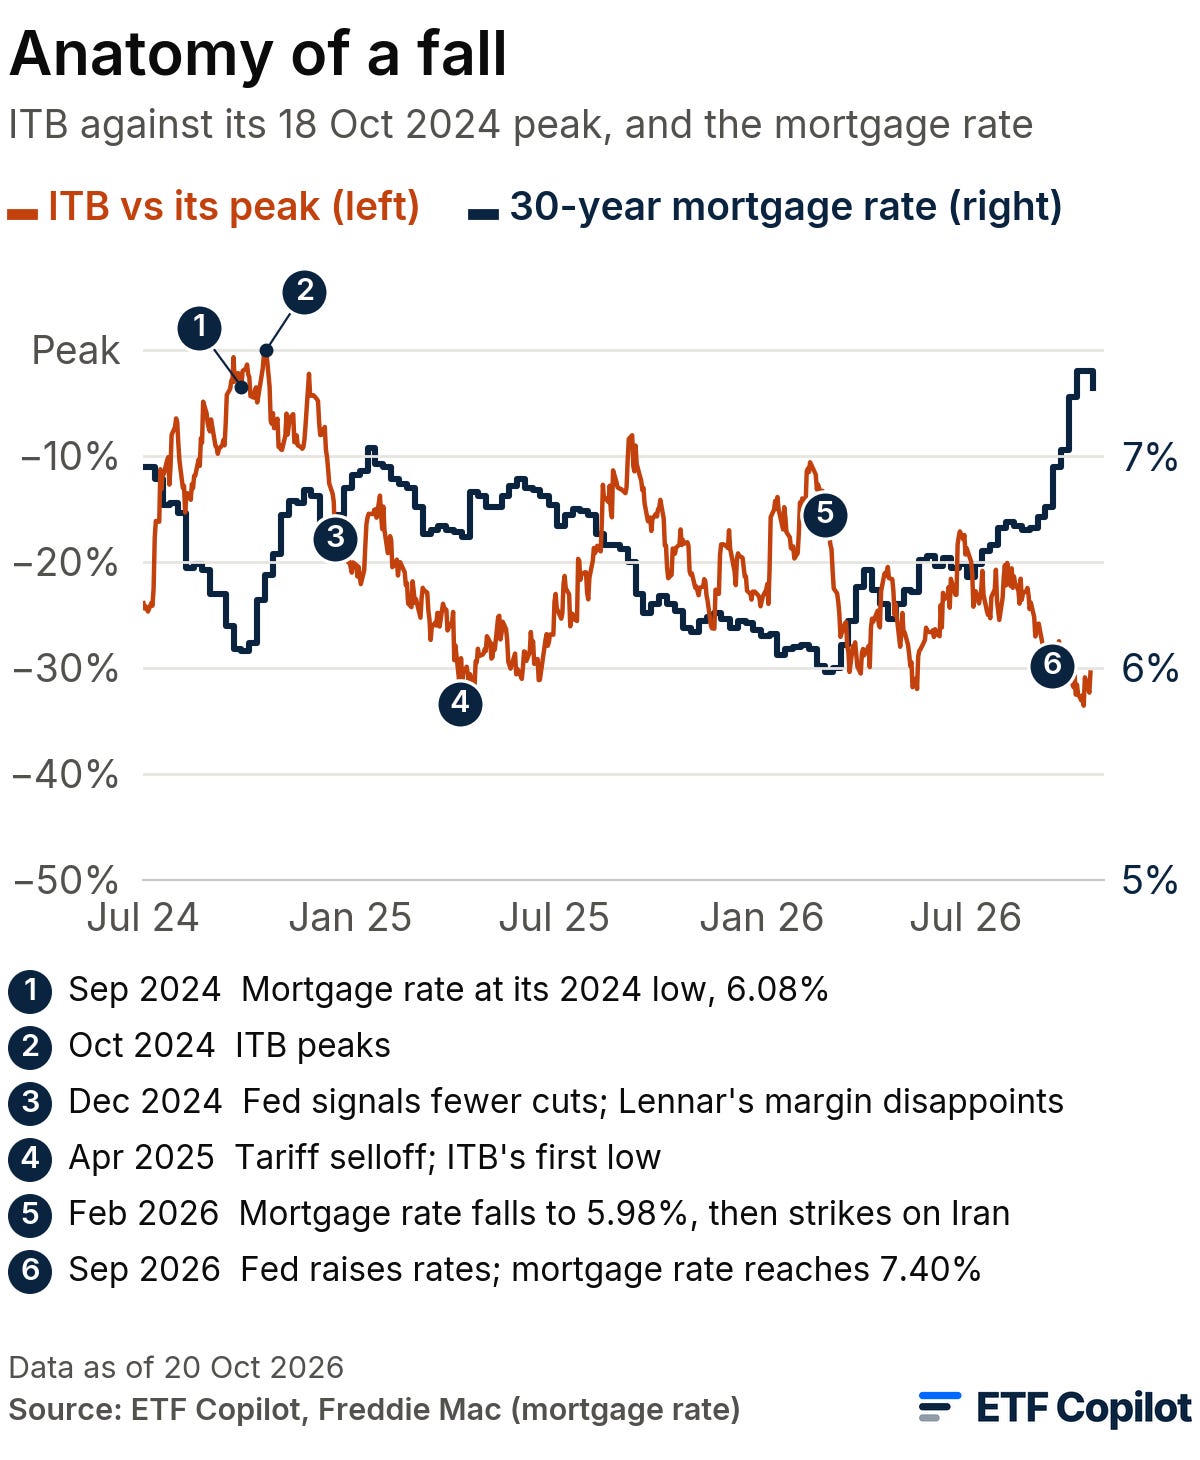
Anatomy of a fall
The top came a month after the Fed's first rate cut of the cycle, on 18 September 2024. Mortgage rates went the other way: the 30-year rate in Freddie Mac's weekly survey bottomed a week after the cut, then rose with Treasury yields after a strong jobs report and the election. By mid-January 2025 it was back above 7%.
Builders' results showed the cost. In December, Lennar's gross margin fell short of its own guidance, on the same day the Fed signaled fewer cuts for 2025. In April, ITB hit its first low in the market-wide tariff selloff.
The fund recovered through the summer, and 2026 brought a second leg. The mortgage rate dipped below 6% in late February, just before the strikes on Iran pushed oil and inflation up. In September the Fed raised its rate, and in October the 30-year rate reached 7.40%, the highest since November 2023. ITB set a new low on 14 October.
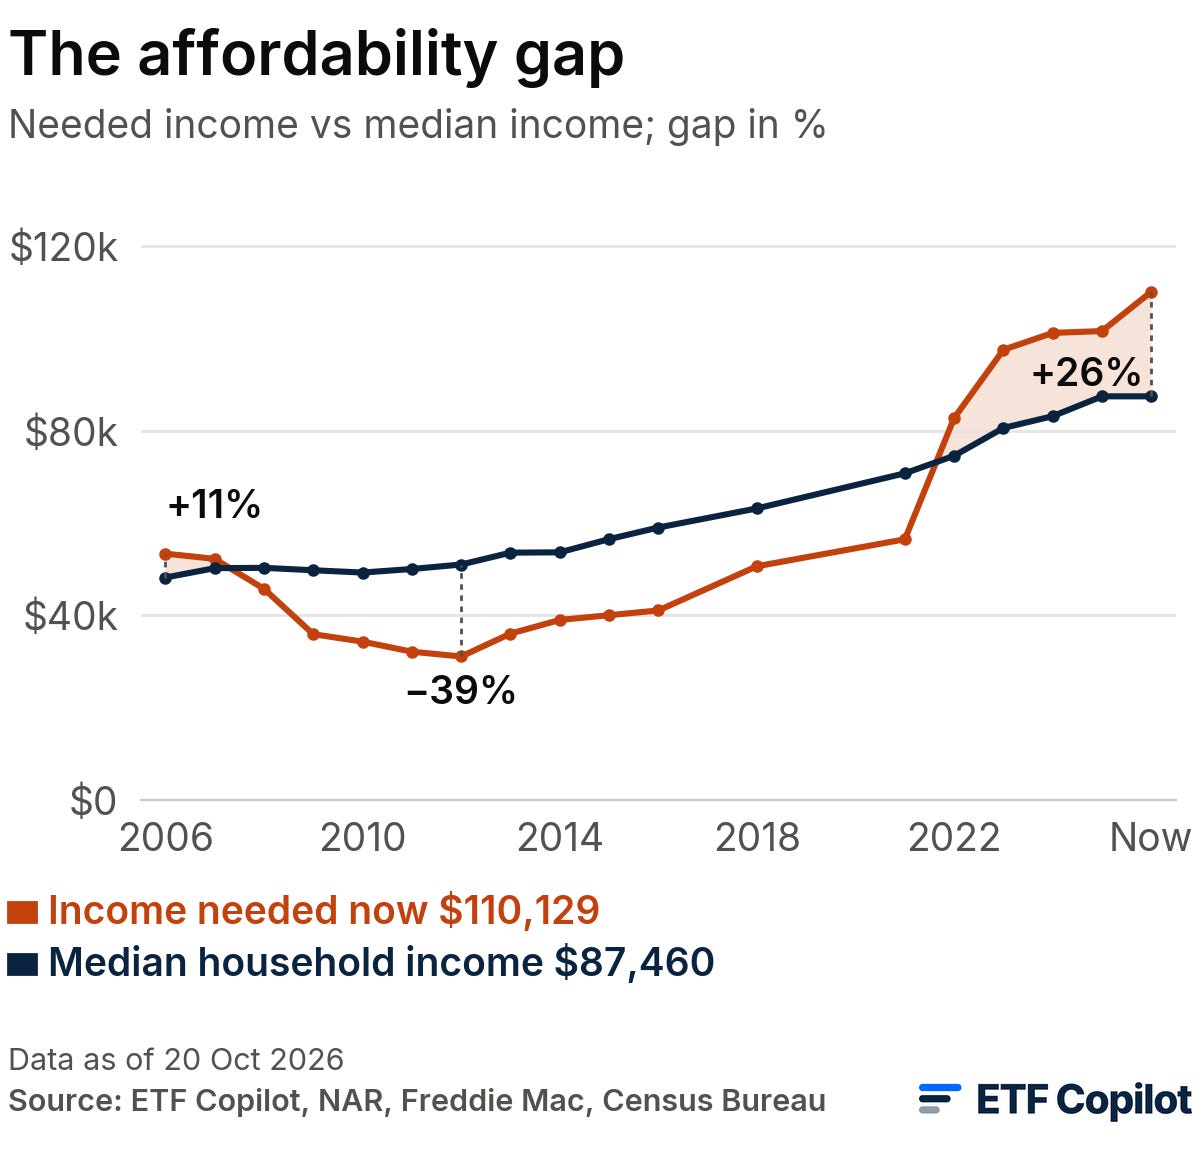
The affordability gap
On our calculation, buying the median existing home at today's mortgage rate takes an income of about $110,000, using the test of the National Association of Realtors, which keeps the loan payment within a quarter of income. The median household earned $87,460 last year, according to the Census Bureau.
The gap is now wider than at the top of the last boom: in 2006 the median home took about 11% more than the median income, and today it takes about 26% more.
Relief may be slow to come. In its October forecast, Fannie Mae raised its outlook for the 30-year rate to 7.5% through 2027. On 9 October, Pimco's chief investment officer Dan Ivascyn told the Financial Times that the 10-year Treasury yield, which mortgage rates track, could reach 6% for the first time since 2000. "You can certainly get there," he said.
Builders pay to close the gap
Builders keep homes selling by paying part of the bill, through price cuts and mortgage rate buydowns. At PulteGroup, incentives were 10.4% of the sale price last quarter, up from 8.9% a year earlier. Lennar's gross margin fell by almost two points from a year before.
Across the industry, 65% of builders used incentives in October, according to the National Association of Home Builders, and its builder confidence index fell to its lowest level since 2012.
Profits fell faster than the price
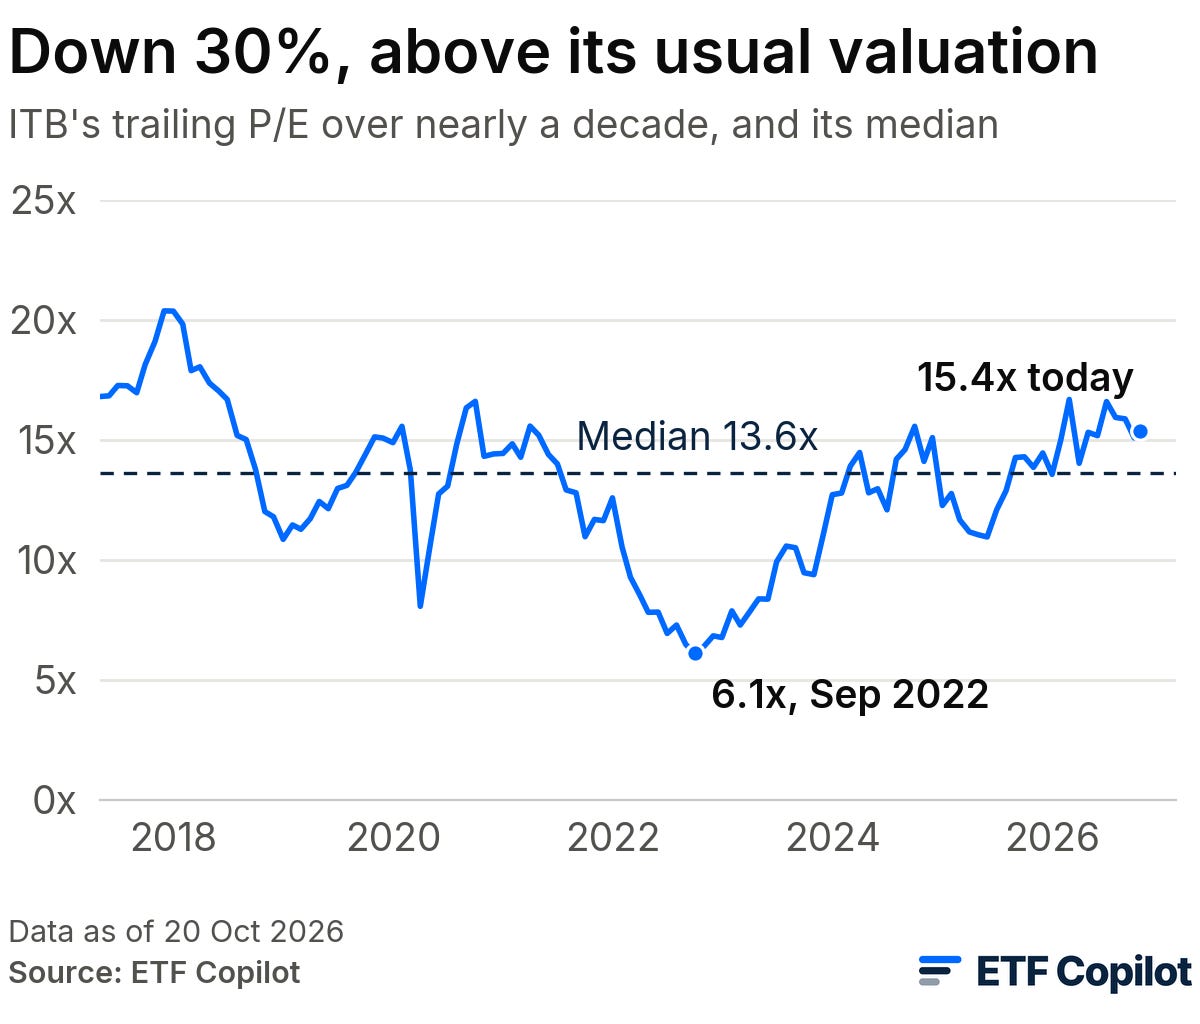
Over the past year ITB returned −15%, while the earnings of the companies inside it fell about 22%. So the fund got more expensive as it fell.
Its trailing P/E is 15.4x, up from 14.1x a year ago and above its median of 13.6x since 2017.
The last downturn ran the other way. From December 2021 to June 2022 ITB fell 41% while builders' earnings were still rising, and by September its P/E had dropped to 6.1x. The fund rebounded in 2023. This time profits are falling along with the price.
The forward P/E of 12.8x shows analysts expect earnings to rise again over the next year. With mortgage rates above 7%, that recovery is the part of the price at risk.
What you own in ITB is mostly the builders. Homebuilders are 64% of the fund, and the four largest, D.R. Horton, PulteGroup, NVR and Lennar, make up 44% on their own. Home Depot, Lowe's and Sherwin-Williams add about 14%. XHB, the other large homebuilder ETF, weights its holdings close to equally, so builders are a smaller part of it, next to building products makers and retailers. It fell less from its 2024 peak, and it trades at a higher multiple.
What comes next
The next week brings three tests. September's new-home sales come out on 27 October, the Fed meets on 27 and 28 October, and D.R. Horton, ITB's largest holding, reports on 29 October. If builders' margins hold, ITB's forward multiple may prove fair. If incentives keep rising, the earnings that multiple assumes may take longer to arrive.
See the full breakdown on ETF Copilot: etf-copilot.com/go/substack/itb-homebuilders
Written by the ETF Copilot research team. Data as of 20 October 2026; mortgage rate as of 22 October 2026. This is not investment advice or a recommendation to buy or sell any security. ETF Copilot receives no compensation from the issuers of the funds mentioned. Managers of ETF Copilot may or may not hold positions in the funds mentioned.
Sources: PulteGroup third-quarter 2024 results; PulteGroup third-quarter 2026 results and presentation; Lennar fourth-quarter 2024 results; Lennar third-quarter 2026 results; Freddie Mac Primary Mortgage Market Survey; Federal Reserve statements of 18 September 2024 and 16 September 2026 and December 2024 projections; NAHB on 2025 tariffs; NAR existing-home sales, September 2026; NAR affordability method; Fannie Mae housing forecast, October 2026; Dan Ivascyn to the Financial Times, via Reuters, 9 October 2026; Census Bureau, Income in the United States: 2025; NAHB/Wells Fargo Housing Market Index; D.R. Horton results date.